Systems · Welfare State · The national balance sheet
We Sold the Future
The triple lock was built to repair a pension Britain allowed to decline. The deeper scandal is what happened to the national wealth that should have made old age easier to finance.
I have often wondered what the average Englishman would feel if he fully understood what this country once owned and what we gave away.
Not simply the industries we allowed to disappear, but the water beneath us, the energy entering our homes, the council houses built with public money, the gas beneath the North Sea and the companies capable of generating an income for generations.
We were told that selling these things made us richer.
People received tax cuts. They were encouraged to buy discounted shares. Those fortunate enough to qualify purchased council houses below market value. Money entered the Treasury, assets entered private hands and, for a while, it must have felt as though everybody was winning.
But the tax cut was spent. The shares were sold. The council houses were not replaced in anything like sufficient numbers. The oil left the seabed. And the assets that once belonged collectively to the country ended up generating rent, dividends and profit for a much smaller group of owners.
Britain behaved as though the good years would never end. Norway understood that one day they would.
Now we hold an annual argument about whether Britain can afford to increase a relatively modest State Pension. Perhaps the more important question is what happened to the wealth that should have made that pension easier to afford.
We sold the assets. We kept the promises. And now we argue about the bill.
The mechanism
What the triple lock actually does
The triple lock sounds more complicated than it is. Every April, the basic and new State Pension increases according to whichever of three figures is highest: inflation, average earnings growth or 2.5%.
Inflation protection prevents pensioners losing purchasing power. Earnings protection prevents them falling behind the working population. The 2.5% floor does something different: when prices and wages are both weak, it deliberately increases the pension relative to them.
The system therefore contains a ratchet. The highest number always applies, but there is no corresponding mechanism that reverses an unusually generous increase when conditions normalise.
But the triple lock was not invented because pensioners were uniquely greedy. It was introduced because the State Pension had been allowed to deteriorate over several decades.
The break
The link Thatcher broke
Before 1980, the basic State Pension was generally expected to rise in line with prices or earnings, whichever grew faster. Margaret Thatcher’s government removed the earnings link.
The pension continued to receive protection against rising prices, but that was not the same as sharing in the country’s prosperity. If prices rose by 3% while wages increased by 6%, pensioners received enough to stand still in the shops while falling behind the people still in work.
Year after year, that difference accumulated. The decision quietly redefined the State Pension. Instead of ensuring that retired people maintained a relationship with national living standards, protection from inflation increasingly became sufficient.
That is why the triple lock cannot honestly be described as nothing more than an electoral bribe. It was a repair mechanism. It responded to a real decline and a real history of pensioner poverty.
The problem is that government never defined when the repair would be complete. There was no destination at which the ratchet would become a stable rule.
The inheritance
Two countries, one sea
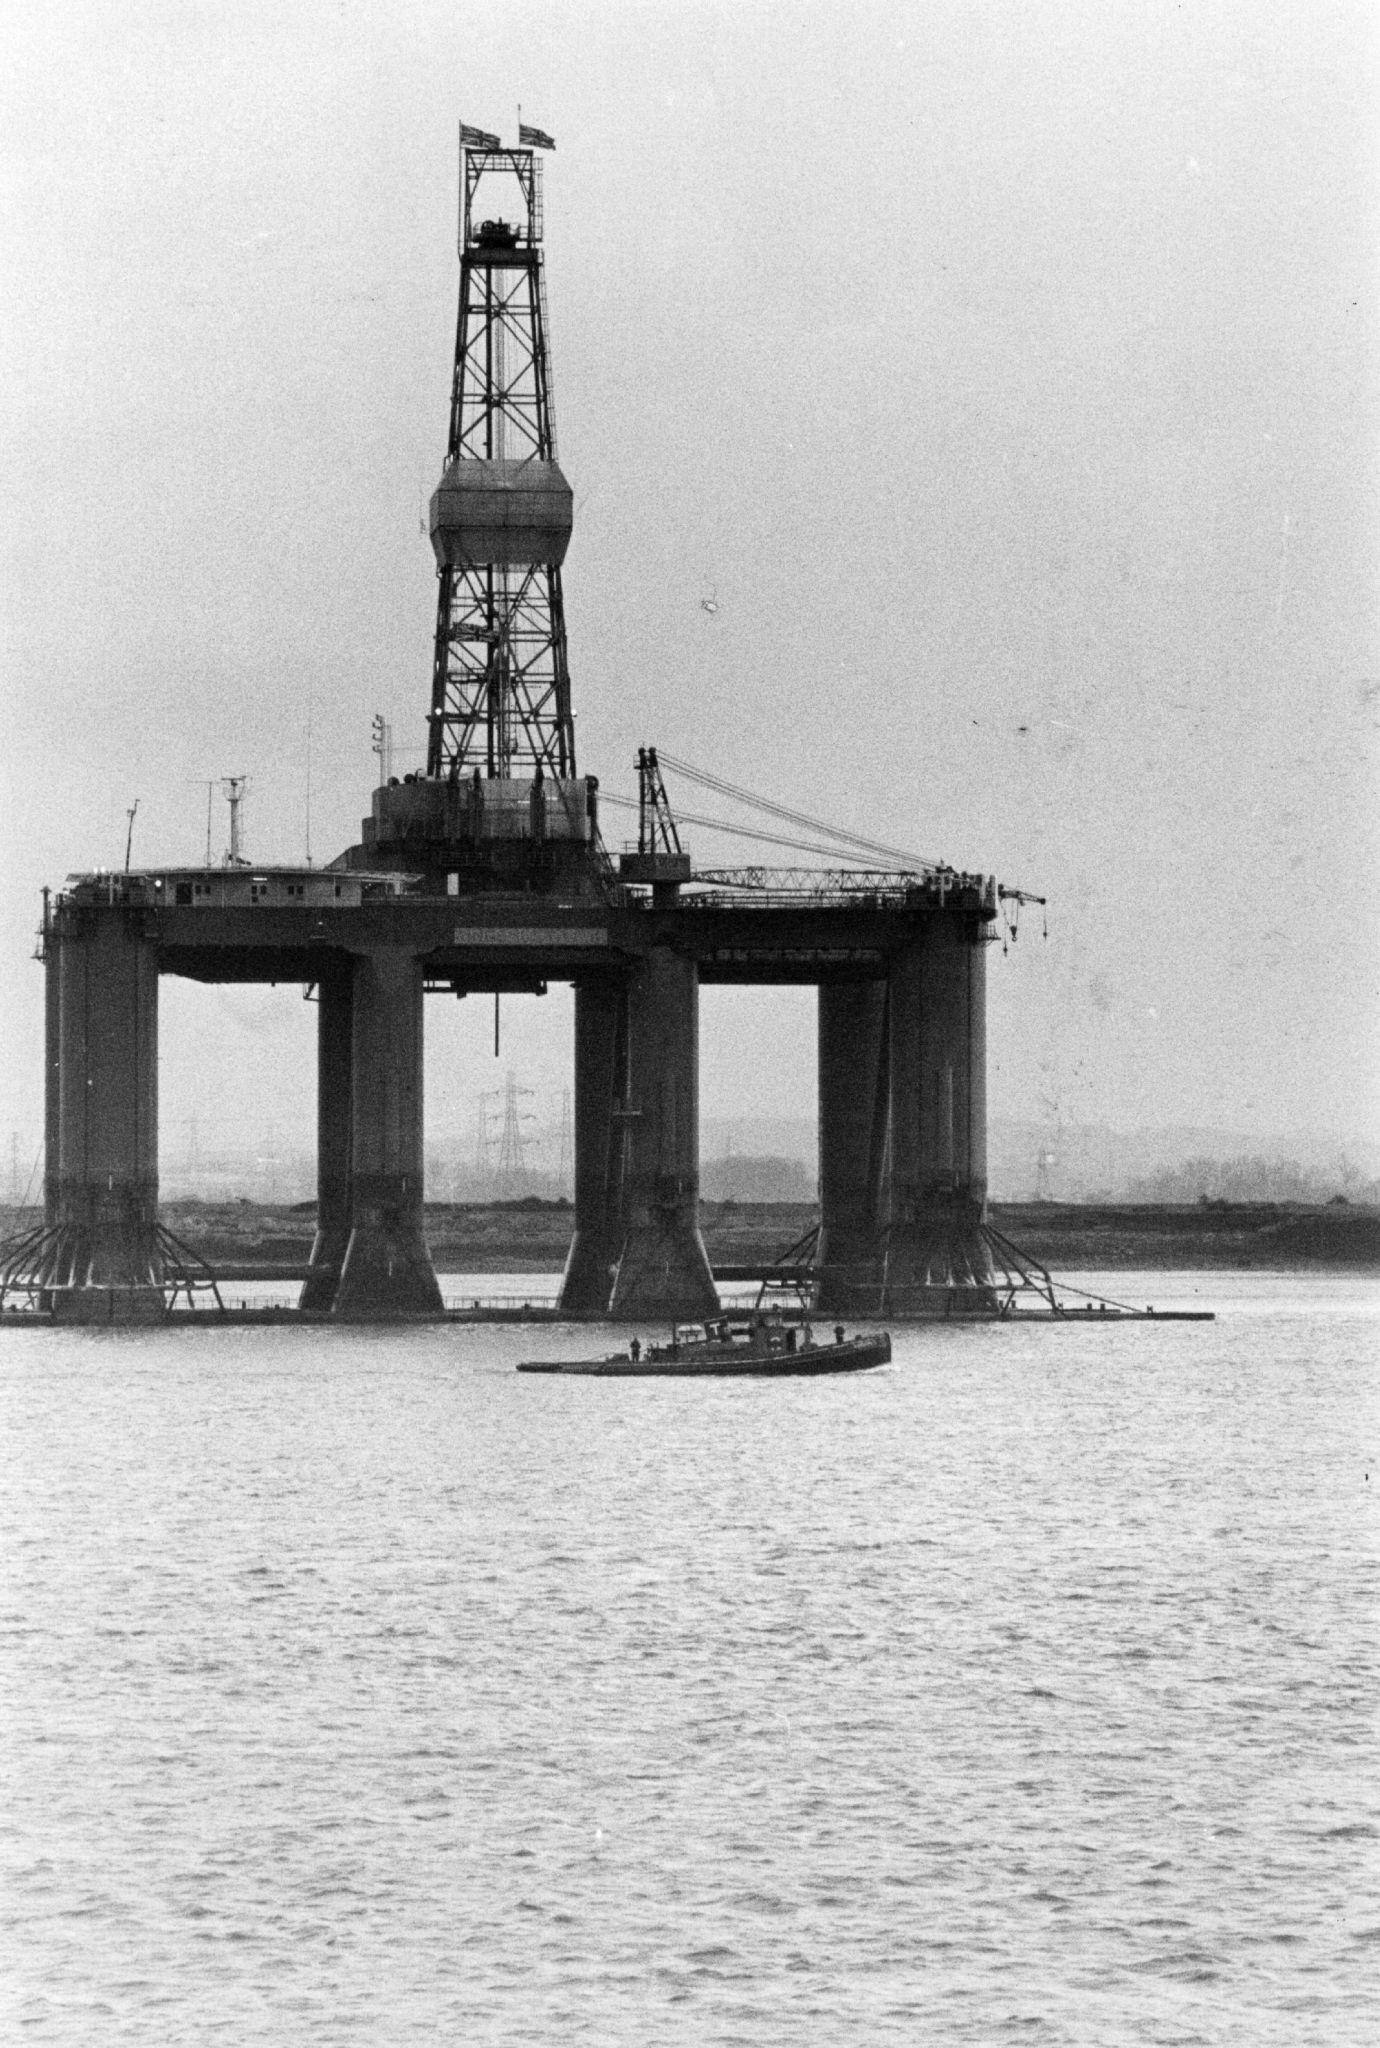
Britain and Norway extracted oil and gas from the same North Sea. They did not extract the same lesson from it.
British North Sea tax revenue peaked in 1984/85 at approximately £12 billion—around 3.4% of the entire economy and more than 10% of total tax revenue.
Britain benefited from that revenue. It helped finance government and supported the economic choices of the period. But it was treated primarily as current income: a finite national resource supporting a state with permanent commitments.
Norway made the harder choice. It maintained higher general taxation, retained stronger public participation in petroleum and transferred oil revenues into what became the Government Pension Fund Global.
By the end of 2025, Norway’s fund was worth approximately NOK 21.3 trillion. More than half its accumulated value came from investment returns rather than direct deposits.
A peer-reviewed simulation estimated that a British fund established in 1975 could have reached approximately £354 billion by 2018. That is not a literal missing bank account, but it establishes that a substantial national inheritance was possible.
Norway turned temporary petroleum income into permanent capital. Britain turned much of its petroleum income into a temporary moment.
Liquidation
The Great British Yard Sale
Between 1979/80 and 1995/96, government raised approximately £81.3 billion in 1995/96 prices through privatisation. That was real money. It would be dishonest to pretend Britain received nothing or that every nationalised business was efficient.
But a sale price is not pure profit. The state exchanged ownership, future dividends and strategic control for money it could spend once.
Water demonstrates the bargain particularly clearly. Private buyers paid approximately £7.6 billion for the regional water authorities. To make the sale possible, government absorbed around £4.9 billion of existing debt and provided the new companies with approximately £1.5 billion in additional public funding.
Ofwat’s records indicate that around £52 billion was distributed in dividends over the following decades. A broader Financial Times calculation placed the figure nearer £78 billion. Different methods produce different totals, but every credible calculation greatly exceeds the original sale price.
Meanwhile, the industry accumulated more than £60 billion of debt. Because water is not an optional consumer product, customers cannot respond by deciding they no longer fancy drinking, washing or flushing a toilet.
Private return. Public necessity. Public risk.
Right to Buy
The houses sold twice
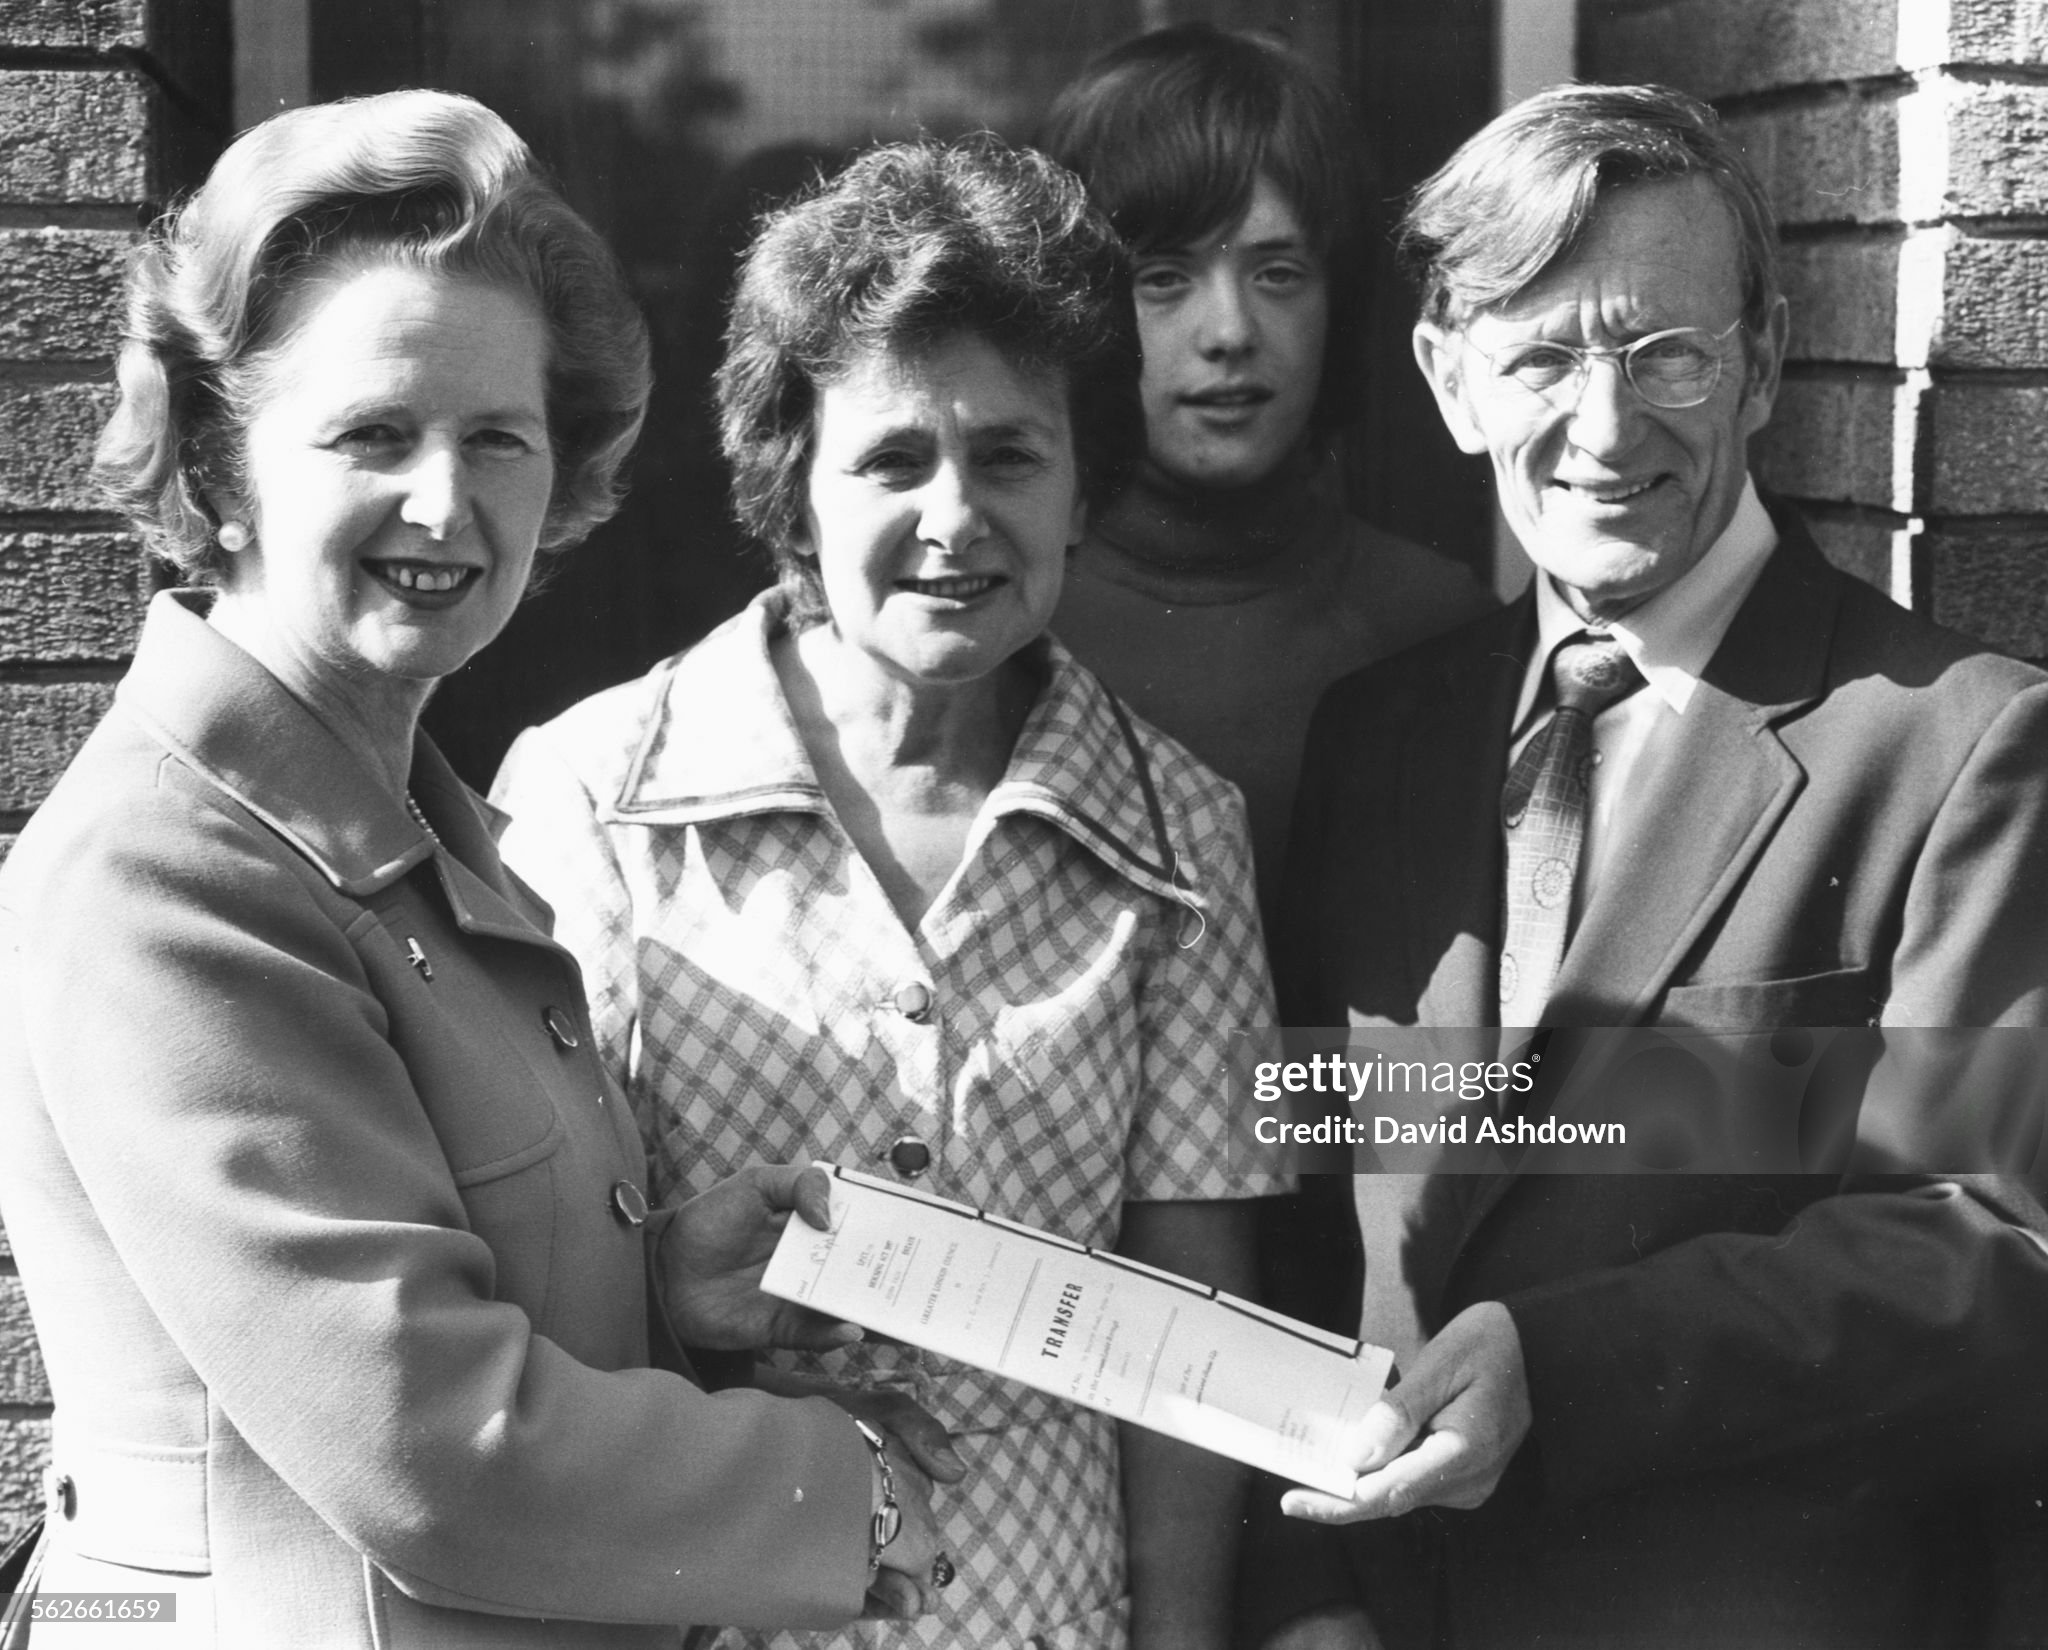
Right to Buy created genuine winners. For tenants able to purchase at a discount, it offered security, ownership and an asset to pass to their children. Any honest examination has to acknowledge that.
But a policy can benefit individuals while damaging the collective balance sheet. Between 1980 and March 2024, more than two million social homes were sold under Right to Buy in England alone.
The failure was not allowing council tenants to become homeowners. It was selling homes at large discounts while preventing councils from replacing the stock on an equivalent scale.
The public built the house. The tenant bought it at a discount. The council lost the rent. In some cases, the state later paid a private landlord to let the same home back to somebody else.
Research across 111 English councils found that more than 40% of identified former council homes in responding areas were subsequently being privately rented. It was not a complete national census, but the direction was unmistakable.
Britain sold the house once at a discount and began paying for it again through the benefits system.
The imitation
Reagan’s revolution, Thatcher’s Britain
Britain likes to remember Thatcher and Ronald Reagan as equal architects of a new economic age. Ideologically, they were partners. Materially, they were not equals.
The United States possessed a continental internal market, enormous natural resources, the global reserve currency, the world’s deepest capital markets, immense defence expenditure and emerging technological power.
Britain possessed valuable industries, North Sea oil, public utilities, skilled workers, council housing and significant financial power. But it did not possess America’s capacity to keep selling, borrowing and consuming while remaining the centre of the global system.
Britain dressed itself in Reaganomics without inheriting America.
Thatcherism borrowed the language of an economic superpower and applied it to a shrinking post-imperial state. Britain was the junior partner attempting a similar experiment with fewer protections and less capacity to recover from failure.
Norway did not need to pretend it was America. It understood what it was: a relatively small North Sea country enjoying a temporary resource windfall. It saved accordingly.
The missed comparison
Scotland and the inheritance already spent
Perhaps the most painful part of the Norwegian comparison is Scotland. It sits beside Norway, shares the North Sea and watched petroleum extracted from waters surrounding it, but taxation and spending decisions were controlled through the United Kingdom.
In 2014, Scottish voters were asked to choose between the familiarity of Westminster and the uncertainties of independence. Oil volatility was repeatedly presented as a risk. Norway demonstrated that volatility was precisely why petroleum revenue should have been converted into permanent financial wealth.
Scotland did not vote against possessing a Norwegian-style fund. By then, most of the historic opportunity to create one had already passed, and Scotland had never controlled the revenue necessary to establish it.
Scotland was asked to judge independence after Westminster had already spent much of the inheritance that could have made independence more secure.
This is not simply a Scottish grievance. The whole United Kingdom could have possessed a national fund. The oil was British when it was extracted. The absence of a fund is British too.
The productive base
The economy left behind
Britain still manufactures important things. It retains strengths in pharmaceuticals, aerospace, specialist engineering, chemicals, defence and advanced technology.
The problem is not that Britain makes literally nothing. The problem is that productive capacity occupies a much smaller place in our economy and political imagination than it once did.
Automation, globalisation and international competition transformed every advanced economy. Britain’s distinctive failure was not that older industries changed. It was that we repeatedly failed to build sufficient productive replacements for what disappeared.
A pension is not paid from memories of work completed 30 years ago. Britain’s State Pension operates predominantly on a pay-as-you-go basis. Today’s workers, employers and taxpayers finance today’s payments.
When productivity and wages grow, supporting pensioners becomes easier. When productivity stagnates and the retired population grows, the same promise consumes more of a weakly expanding economy.
The triple lock is not becoming difficult because pensioners receive too much. It is becoming difficult because Britain has produced too little growth.
The people behind the policy
The poverty the triple lock repaired
None of this means pensioners are living extravagantly. The full new State Pension in 2026/27 is £241.30 per week—approximately £12,548 per year. Britain’s public pension remains low relative to earnings compared with many advanced economies.
There are also enormous differences between pensioners. Some own valuable mortgage-free homes, receive substantial private pensions and possess significant savings. Others rent, live alone and depend almost completely on the State Pension and means-tested support.
The same triple-lock increase therefore performs entirely different functions. For one pensioner, it helps pay the heating bill. For another, it enters an account already receiving more private pension income each week than many workers earn.
Protecting pensioners from poverty is a social obligation. Giving every pensioner the most favourable of three calculations forever is a political choice.
The boundary
Common sense isn’t that common
Common sense says limited public support should go first to those who need it. But every attempt to target support encounters the same objection: somebody will sit just above the threshold.
Every boundary creates edge cases. That does not logically mean there should be no boundary at all.
Britain applies thresholds, tapers, caps and assessments throughout the working-age benefits system. Yet when support for affluent pensioners is questioned, administrative simplicity suddenly becomes sacred.
“Somebody might miss out” sounds compassionate. In practice, it often protects those furthest from hardship.
But means-testing the entire State Pension would create serious problems. Pension Credit demonstrates them: roughly one-third of eligible pensioners fail to claim it, often because of confusion, stigma or the belief that they will not qualify.
A better settlement
- Preserve a universal State Pension floor.
- Choose a declared target relative to average earnings.
- Guarantee that inflation can never erode it.
- Replace the endless ratchet once the target is reached.
- Recover additional universal payments progressively through taxation from high-income pensioners.
- Automate Pension Credit wherever government records demonstrate entitlement.
No humiliating application for the poorest. No crude cliff edge. No pretence that tapering is impossible. And no automatic assumption that accumulated affluence deserves precisely the same protection as poverty.
The national habit
Everyone is entitled
Britain’s culture of entitlement does not begin with the poor. It runs through every class.
- Pensionersfeel entitled because they paid National Insurance.
- Homeownersexpect permanently rising property prices.
- Landlordsexpect rents to service private investments.
- Shareholdersexpect permanent utility dividends.
- Companiesexpect subsidies, contracts and rescue packages.
- Governmentsmake promises without preserving the assets needed to finance them.
Everybody has been encouraged to believe that their own claim is earned, natural and untouchable. Only the person beneath them is receiving a handout.
Britain did not become entitled because poor people demanded too much. It became entitled because the political system taught every group to protect its own claim while refusing to acknowledge who would eventually pay.
The mentality
A country still living in the Victorian era
Britain congratulates itself on being modern while reproducing something recognisably Victorian.
Assets concentrate at the top. People underneath pay rent, bills and interest for access to necessities. Private owners collect income from housing and infrastructure built or supported by earlier generations.
Assistance remains available to the poor, but only after they navigate assessments designed to distinguish the deserving from the undeserving.
Norway made different choices because its institutions behaved as though natural wealth carried an obligation to people not yet born. Britain’s institutions behaved as though everything had a price and whoever could purchase it had earned the right to extract from it.
Norway cared for its people not merely by spending money upon them. It cared by refusing to leave future governments empty-handed.
The monument
The statue survives
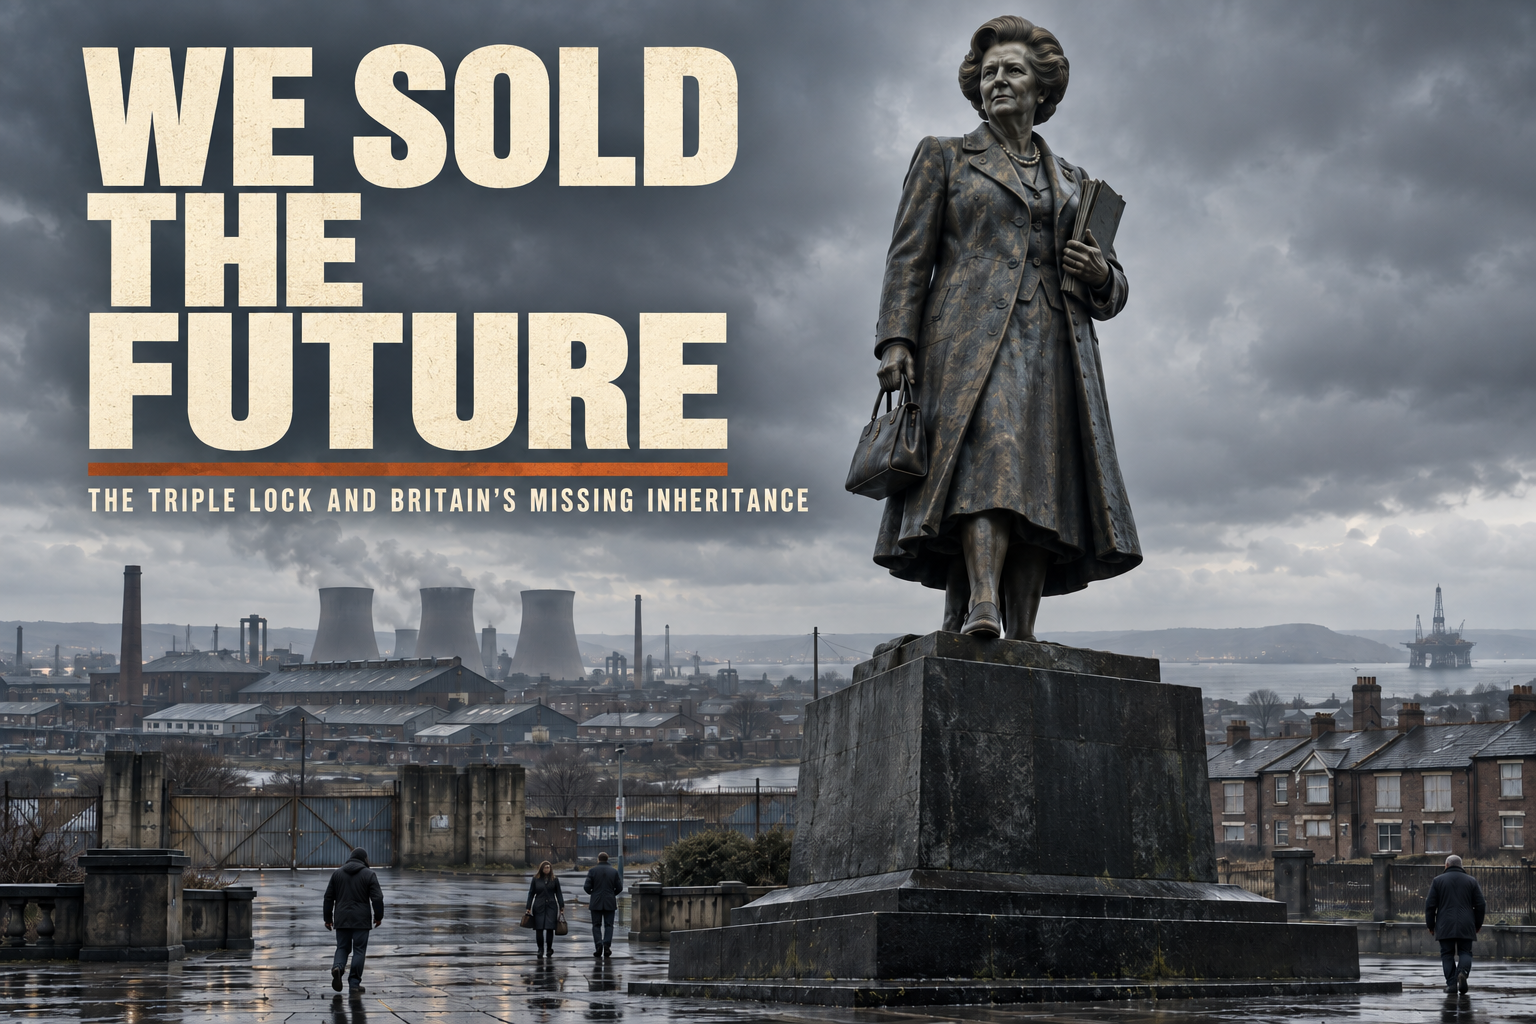
Britain erected a statue to Margaret Thatcher: the prime minister whose government broke the pension’s earnings link, accelerated the sale of public housing, privatised national industries and established an economic settlement every subsequent government largely accepted.
The statue matters because Britain memorialised the beginning of the transformation while refusing to account honestly for its destination.
We celebrated the sale. We ignored the balance sheet. We admired the temporary prosperity. We left later generations to discover what was missing.
The statue survives.
Much of the inheritance does not.
The conclusion
We sold the assets but kept the promises
The triple lock is not evidence that Britain has been too generous. It is evidence that Britain is attempting to protect old age through annual taxation after spending, selling or surrendering much of the wealth that could have supported it permanently.
It was introduced because the State Pension had been allowed to decline relative to earnings. It remains necessary because Britain’s public pension is modest and too many pensioners still face poverty.
It remains controversial because its open-ended design protects affluent and impoverished pensioners alike while transferring an unpredictable cost to a working population experiencing weak wages, expensive housing and deteriorating services.
The answer is not to return pensioners to poverty. It is to decide what a dignified State Pension should be worth relative to earnings, guarantee that inflation can never erode it and replace the endless ratchet with a transparent long-term settlement.
A country cannot repeatedly sell income-producing assets, neglect productive investment, consume temporary windfalls and then act surprised when permanent obligations become difficult to finance.
Norway turned finite resources into an inheritance. Britain turned much of its inheritance into a receipt. For a while, we thought the receipt made us rich. Now we are left arguing about who can afford the promises written on the back.
Research notes and principal sources
Pensions: House of Commons Library briefings on the triple lock, State Pension uprating and international comparisons; Department for Work and Pensions pensioner income and poverty statistics; Institute for Fiscal Studies Pensions Review; Office for Budget Responsibility fiscal sustainability reporting.
Oil and Norway: HMRC and OBR North Sea receipts; Norwegian Ministry of Finance and Norges Bank Investment Management; Atkinson and Hamilton’s peer-reviewed sovereign wealth fund simulation.
Privatisation and housing: National Audit Office reports; House of Commons Library privatisation, water ownership and Right to Buy briefings; Ministry of Housing Right to Buy statistics; Ofwat financial-resilience data.
Important: The £354bn UK fund is a modelled counterfactual. Water dividend totals vary by methodology: roughly £52bn in Ofwat records and approximately £78bn under the broader Financial Times calculation.